Payment Onboarding Checklist for Small Online Teams
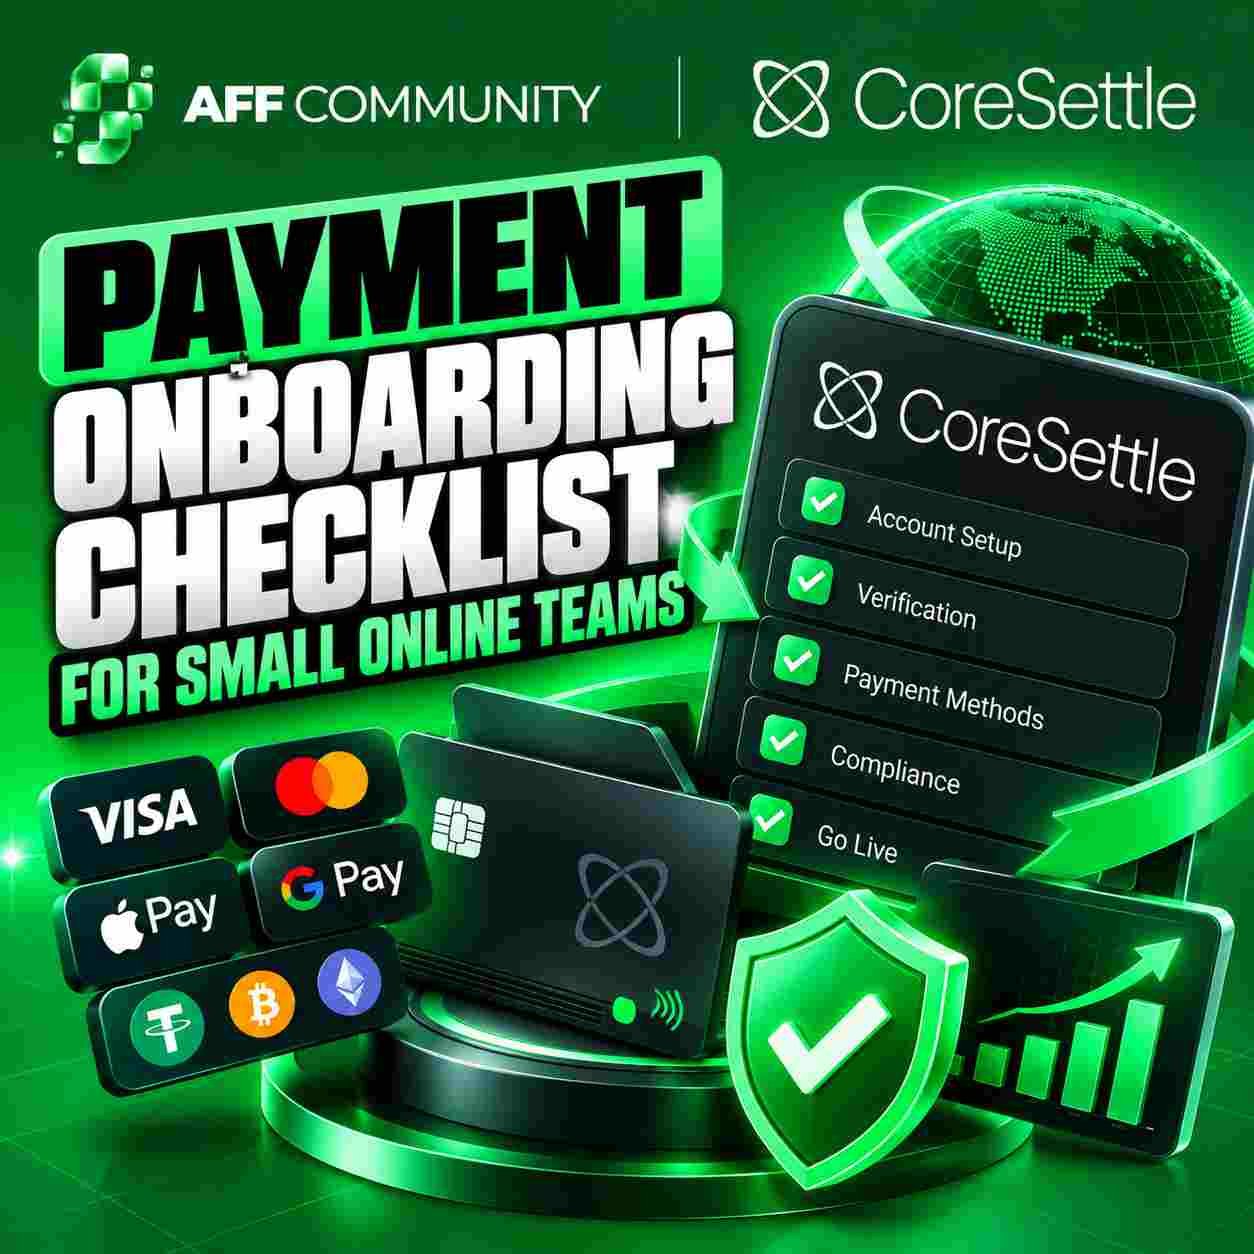
Payment onboarding becomes easier when operations and compliance prepare the same checklist. This guide focuses on the decisions, evidence and trade-offs that matter in a real workflow. It is an educational explanation, not a claim of hands-on testing or guaranteed outcomes. For the relevant service context, see CoreSettle. Features, availability and prices should be checked on the official site before publication.
Example: A small retailer wants to launch checkout but has inconsistent legal names across its website and documents. The team records the starting conditions and the decision it needs to make before touching the tool. The result is judged against that decision, not against a marketing claim.
Before you begin: scope and safeguards
Start with the business purpose, responsible owner and written permission where relevant. Identify what is in scope, which data may be collected and when the work should stop. A small, well-documented pilot is usually more informative than a broad rollout with no baseline.
Create a compact evidence log: date, test condition, observation, decision and next owner. Keep passwords, tokens and customer records out of screenshots. If another colleague cannot reproduce the decision from the log, the documentation is not finished.
Step-by-step implementation
1. Map the checkout journey
Action: Document products, pricing, currencies and customer countries. Write down the assumption you are testing and the evidence that could disprove it. A screenshot alone rarely explains what happened; include the environment and a short note about why the result matters.
Quality check: The purchase path is understandable. A reviewer should be able to identify the input, outcome and unresolved risk without rerunning the entire procedure.
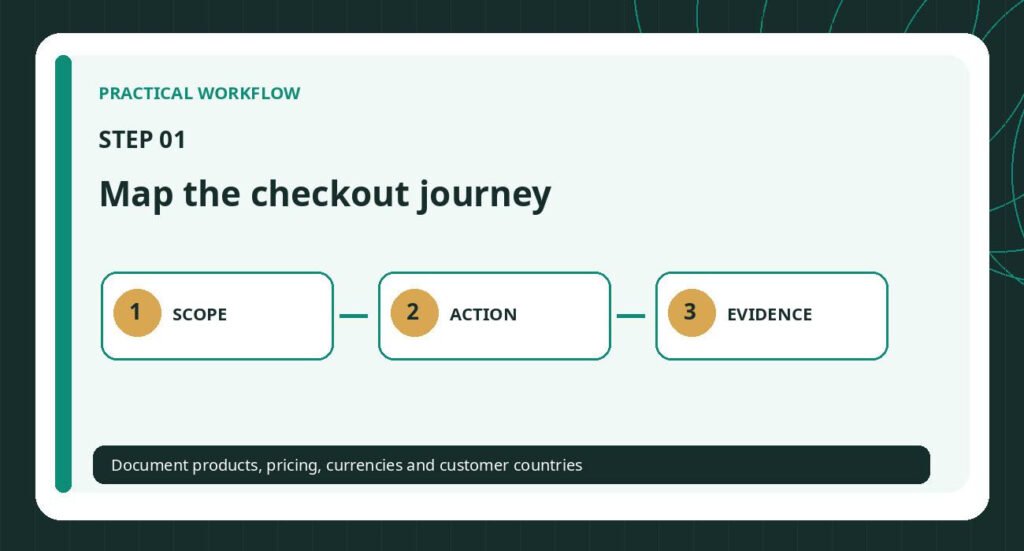
Figure 1. Map the checkout journey
2. Prepare business details
Action: Collect legal identity, contact information and required policies. Assign a clear owner and a deadline to this decision. When a provider, browser or payment system has several options, change one parameter and keep the rest stable so the effect is interpretable.
Quality check: The documents are current and consistent. If the observation does not support a decision, mark the result inconclusive rather than inventing certainty.
3. Review risk controls
Action: Define access rights, fraud review and refund responsibilities. Capture the observed response as well as the expected response. If there is a mismatch, separate a configuration error from a product limitation before attempting another run.
Quality check: No single person controls everything. A reviewer should be able to identify the input, outcome and unresolved risk without rerunning the entire procedure.
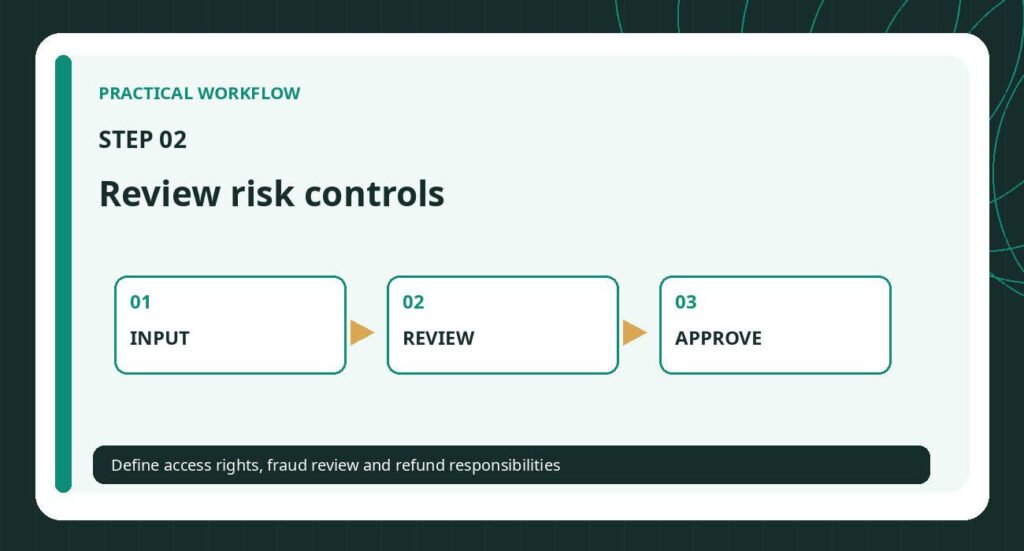
Figure 2. Review risk controls
4. Test payment states
Action: Exercise success, decline, refund and webhook scenarios in sandbox. Look beyond the successful path. Ask what happens if the session expires, a message is delayed, a customer requests a refund or a colleague needs to take over the work.
Quality check: Each state produces the right customer message. If the observation does not support a decision, mark the result inconclusive rather than inventing certainty.
5. Launch with monitoring
Action: Watch reconciliation, support requests and error rates. Close the loop by recording what should change in the operating procedure. The final deliverable is not a collection of screenshots; it is a decision the team can explain and repeat.
Quality check: Owners can respond to incidents. A reviewer should be able to identify the input, outcome and unresolved risk without rerunning the entire procedure.
Figure 3. Launch with monitoring
Common failure mode and corrective action
A frequent mistake is: Going live before testing failed payments and refunds. A better response is to stop the workflow, check the original requirement and isolate the smallest reproducible example. Record the correction in the same log as the initial attempt so the team learns from the incident rather than merely repeating it.
A useful second review asks three questions: What is the strongest evidence? Which assumption could be wrong? What would change the recommendation? Resolve business identity, refund rules and support contacts before integration work.
How to measure the outcome
Primary indicator: successful payments and support cases per 100 orders. Read this together with quality guardrails such as support workload, incident severity, consent complaints and the amount of manual rework. A faster workflow is not necessarily better if it increases risk or produces misleading evidence.
Compare like with like: the same time window, traffic type, region, sample definition and test environment. Note sample size and exceptional events. Small samples are useful for debugging but should not be presented as universal performance benchmarks.
Final editorial and operational checklist
☐ The activity is permitted and documented.
☐ Sensitive information is excluded from images and logs.
☐ Steps can be reproduced by a colleague.
☐ Claims are supported or clearly qualified.
☐ A responsible owner is named for follow-up.
Editorial disclosure: This guide is educational. Provider links identify relevant tools, while standards and documentation links support background reading. No independent product test, search-ranking guarantee or third-party originality score is claimed.